Address
Nanlang Industrial Zone, Xingtan Town, Shunde District, Foshan, Guangdong, China
Work Hours
Mon–Fri, 9:00 AM – 6:00 PM (CST/UTC+8). We aim to respond to all inquiries within 48 hours.

Address
Nanlang Industrial Zone, Xingtan Town, Shunde District, Foshan, Guangdong, China
Work Hours
Mon–Fri, 9:00 AM – 6:00 PM (CST/UTC+8). We aim to respond to all inquiries within 48 hours.
When you’re pulling fabric swatches and calculating cut-and-sew costs, the actual transfer of money often takes a backseat. But if you’ve ever sourced textiles from overseas, you know that payment terms textile agreements dictate your entire production timeline. One mismatched clause can freeze your working capital for weeks. Another can leave you staring at a container of off-spec fabric with zero leverage. I’ve seen brands get tripped up by the jargon because nobody explained how these structures actually interact with dye scheduling, QC inspections, and freight forwarding. It’s not just about wiring money. It’s about aligning cash flow with production milestones.
In this guide, we’ll break down how each method works, where the hidden friction points are, and how to structure agreements that protect your margins without strangling supplier relationships.
Payment terms define when, how, and how much you remit to a mill or finishing house. They’re the financial skeleton of any apparel sourcing deal. In international textile trade, especially with China-based manufacturers, these structures shift based on order volume, relationship history, and perceived risk. Most brands default to three or four standard models. Telegraphic transfers handle the heavy lifting for bulk rolls. Letters of credit step in when order values climb or trust is still being built. Digital wallets and cards cover sample development. Net terms usually only appear after years of consistent volume.
Negotiation rarely happens in a vacuum. You’ll typically settle these details during initial onboarding calls. The mill will present their standard structure, and you’ll counter based on your cash cycle and risk tolerance. It helps to map payment milestones to actual production checkpoints. For example, tying a balance release to a passed AQL 2.5 inspection on a 300 GSM French terry order prevents you from funding unfinished goods. Always get the final agreement in writing. Verbal promises dissolve quickly once fabric hits the dyeing stage.
I prefer keeping the payment table visual so designers can scan it during supplier calls. It saves time and removes ambiguity.
| Method | Best For | Transaction Speed | Risk Profile |
| T/T | Bulk production | 2–3 business days | Moderate to high |
| L/C | Large or first orders | 5–10 business days | Low for both parties |
| PayPal/Card | Samples and prototyping | Instant | Low for buyer |
| Net 30/60 | Established partners | Post-delivery | High for supplier |
Understanding these baseline structures keeps your procurement workflow predictable. You can align payment schedules with dye house capacities and cutting room availability. That alignment prevents bottlenecks before they start.
Telegraphic transfer, or wire transfer, moves funds directly between banking institutions. It remains the workhorse for textile bulk orders worldwide. Clearing typically takes two to three business days, depending on correspondent banks and compliance checks. The standard structure in apparel sourcing leans heavily on milestone-based splits. You’ll usually see a thirty percent deposit requested before cutting or dyeing begins. The remaining seventy percent clears before the bill of lading releases. Repeat clients often negotiate down to a twenty percent upfront hold, with the balance triggering only after goods pass quality inspection.
The appeal is straightforward. Transaction fees stay low. Processing moves fast. Suppliers trust the liquidity, which often translates to better dye lot allocation and priority cutting slots. The downside is real. Once those wires clear, you have zero recourse if the mill misses weight specifications or delays shipment. Funds don’t bounce back automatically. You’re relying entirely on contractual leverage and supplier reputation.
I remember working with a startup launching a heavyweight fleece collection. They initially pushed for fifty percent net terms. The mill flatly refused. After three weeks of back-and-forth, they realized the friction was costing them fabric availability. They compromised on a twenty-eight percent deposit, tied the final balance to a third-party inspection report, and built a small penalty clause for GSM deviations over five percent. It wasn’t perfect, but it kept the production line moving.
They also learned that mismatched SWIFT routing details can hold transfers for extra days. Double-checking bank coordinates before wiring saves precious lead time. All T/T terms are outlined in our full terms and conditions, so you know exactly where the legal boundaries sit before wiring anything.
A letter of credit operates as a bank-backed guarantee. Your financial institution promises to pay the supplier once they present documents proving shipment and compliance. It’s governed by international standards, specifically the ICC’s UCP 600 rules. The process feels mechanical at first. You apply with your bank, detailing exact specifications like fabric composition, shrinkage tolerance, and container load numbers. The supplier manufactures, then submits a commercial invoice, packing list, and often a quality certification. Your bank scrutinizes every comma. If the paperwork aligns perfectly, funds release.
This structure shields both sides. You avoid prepaying for substandard goods. The supplier secures payment assurance regardless of your cash flow hiccups. The trade-off involves complexity and cost. Setup fees usually range between one and three percent of the total order value. Banks charge amendment fees if you tweak dye shades mid-production. Strict compliance means a misplaced decimal on a weight declaration can stall your entire shipment. I’ve watched brands lose two weeks over a single mismatched tracking number.
Reserve this method for orders exceeding fifty thousand dollars. It also makes sense when vetting a new finishing mill or sourcing from high-risk regions. Contact our team Contact our team to discuss L/C options for your large orders, and we’ll walk you through the documentary requirements upfront.
Digital payment channels stick to sampling and low-value development. You’ll see them used for swatch kits, strike-offs, and prototype panels. They work well when you’re testing fiber blends or validating hand feel before committing to a production roll. Processing happens instantly. Dispute resolution sits on your side if the delivered sample drastically differs from the swatch card.
The friction emerges in fees. Suppliers absorb transaction costs that hover around three to five percent. Those margins disappear quickly when scaling to bulk dyeing. You’ll never see a legitimate mill suggest PayPal for a ten-thousand-meter order. It’s economically unviable. Quick note: I once chased a sample fee deduction for three months because the initial email didn’t specify the minimum bulk threshold. Always verify the deduction cap before paying.
Our standard practice requires full payment upfront for all sampling. We deduct those fees automatically from your first bulk order, provided the minimum reaches five hundred meters. It keeps the development pipeline clean and predictable. Digital channels are fine for lab dips and tension tests, but they shouldn’t dictate your production budget.
Money changes hands faster than fabric moves through the dye house. That speed creates vulnerability. Supplier non-performance ranks as the top concern. You wire a deposit, and the mill reallocates the capacity to a larger buyer. Quality disputes follow closely. You pay in full before inspection, only to receive fabric with uneven tension or color variance exceeding the accepted delta E threshold. Fraudulent operations also exist, though they’ve become more sophisticated. Shell companies mimic legitimate mills, collect deposits, and vanish before looms even start.
Mitigation starts with verification. Cross-check business registrations, request recent factory audit reports, and verify years of continuous operation. A mill with twenty-plus years in the market operates differently than a newly registered trading company. Use escrow services or documentary credits for initial runs. Never fund one hundred percent upfront. Staged payments aligned with actual production checkpoints remove the guesswork.
I recommend tying final releases to third-party inspections. Independent auditors verify GSM, tear strength, and shrinkage rates before you cut the check. It costs a fraction of a replacement order. First orders demand L/C or escrow structures. Trusted repeat suppliers justify T/T splits. Samples stay on digital channels. Mapping payments to physical milestones keeps your cash flow healthy and your inventory specs accurate.
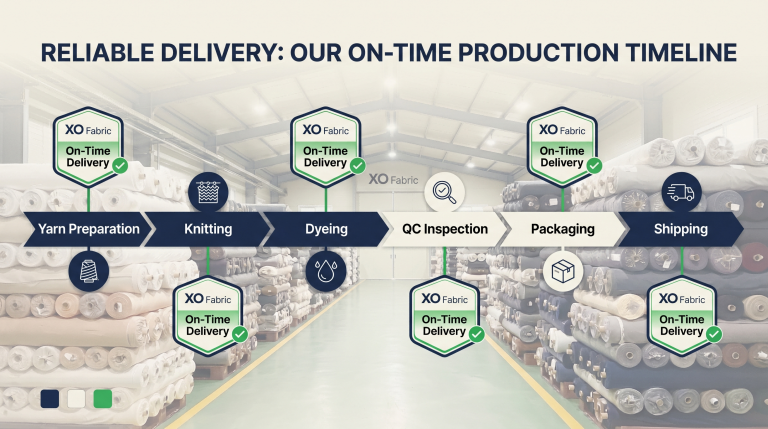
We structure our financial terms to match real production cycles rather than arbitrary banking deadlines. Bulk orders follow a thirty percent deposit model, with the remaining seventy percent clearing before we release the bill of lading. Repeat clients who’ve completed three or more successful runs can negotiate down to a twenty percent upfront hold. This shift rewards consistent volume and stable communication.
Sample development moves differently. We require one hundred percent payment before cutting or dyeing test panels. It prevents half-finished prototypes from clogging the lab. We accept telegraphic transfers as the primary channel for production volumes. Letters of credit apply to orders surpassing fifty thousand dollars, with bank charges remaining the buyer’s responsibility. Digital wallets and cards handle sampling exclusively, with US clients enjoying streamlined card processing.
The framework exists to protect both your cash flow and our manufacturing capacity. We’ve refined these terms across two decades of textile production, balancing risk while keeping the supply chain fluid. Full payment terms are outlined in our terms and conditions, so you can review every clause before signing. Contact our team Contact our team to discuss custom payment terms for your brand, and we’ll tailor a structure that fits your production calendar.
Payment structures dictate more than your quarterly cash flow. They shape supplier trust, determine inspection timelines, and influence how quickly your fabric moves from loom to cut table. Whether you’re wiring deposits for repeat orders, leveraging documentary credits for large first runs, or tapping digital channels for sampling, the goal remains identical. Align your financial milestones with actual production checkpoints. Verify compliance before releasing balance payments. Protect your margins without suffocating the partnership.
We keep our terms transparent because predictable manufacturing requires predictable communication. Twenty years of in-house production, a dedicated technical team, and a fully controlled dyeing workflow mean we don’t rely on opaque financial clauses to manage risk. Ready to start your next textile order? Contact our team Contact us today to discuss payment terms and request samples. We’ll map out a structure that fits your lead times and quality standards.